Why China won’t ban housing presales outright
China's property sector, now in its sixth year of decline, saw significant policy shifts in late August 2026. Chinese courts initiated liquidation proceedings for China Evergrande Group's onshore business and sentenced its founder, Hui Ka-yan, to life imprisonment for financial crimes. This was followed by coordinated announcements from the central bank, housing ministry, and financial regulators, introducing new rules for property development financing. The new "property development model" aims to replace the previous leverage-driven system, with a focus on tighter oversight of housing presale funds. Regulators will now deny developers access to homebuyers' mortgage money until projects are delivered, addressing the misuse of presale funds that led to unfinished projects and public anger.
Beijing's recent policy actions in late August 2026, including the liquidation of China Evergrande Group and new financing rules, are not a move to ban housing presales outright. Instead, the focus is on reforming the system to prevent the misuse of presale funds. Regulators are tightening oversight and restricting developers' access to homebuyers' mortgage money until project delivery, a direct response to the financial instability and social risks caused by unfinished projects. The new "property development model" aims to unwind the debt-fueled growth that characterized China's real estate sector. While the intent is to foster a healthier market, the challenge lies in balancing this reform with avoiding a broader financial crisis. The immediate impact will be felt by developers across China, who will face stricter capital controls and a reduced reliance on upfront presale financing. This shift could slow new project starts and completions in the short term, but it is intended to stabilize the market in the long run. For Asia's broader financial markets, the measured approach to property sector reform in China suggests Beijing is prioritizing stability over drastic measures. The move to address deep-seated issues like presale fund misuse, rather than a blanket ban, indicates a calculated effort to manage systemic risk. The thing to watch is how effectively these new regulations are enforced and whether they genuinely restore homebuyer confidence in a sector that has been in decline for six years.
Related reading
6 stories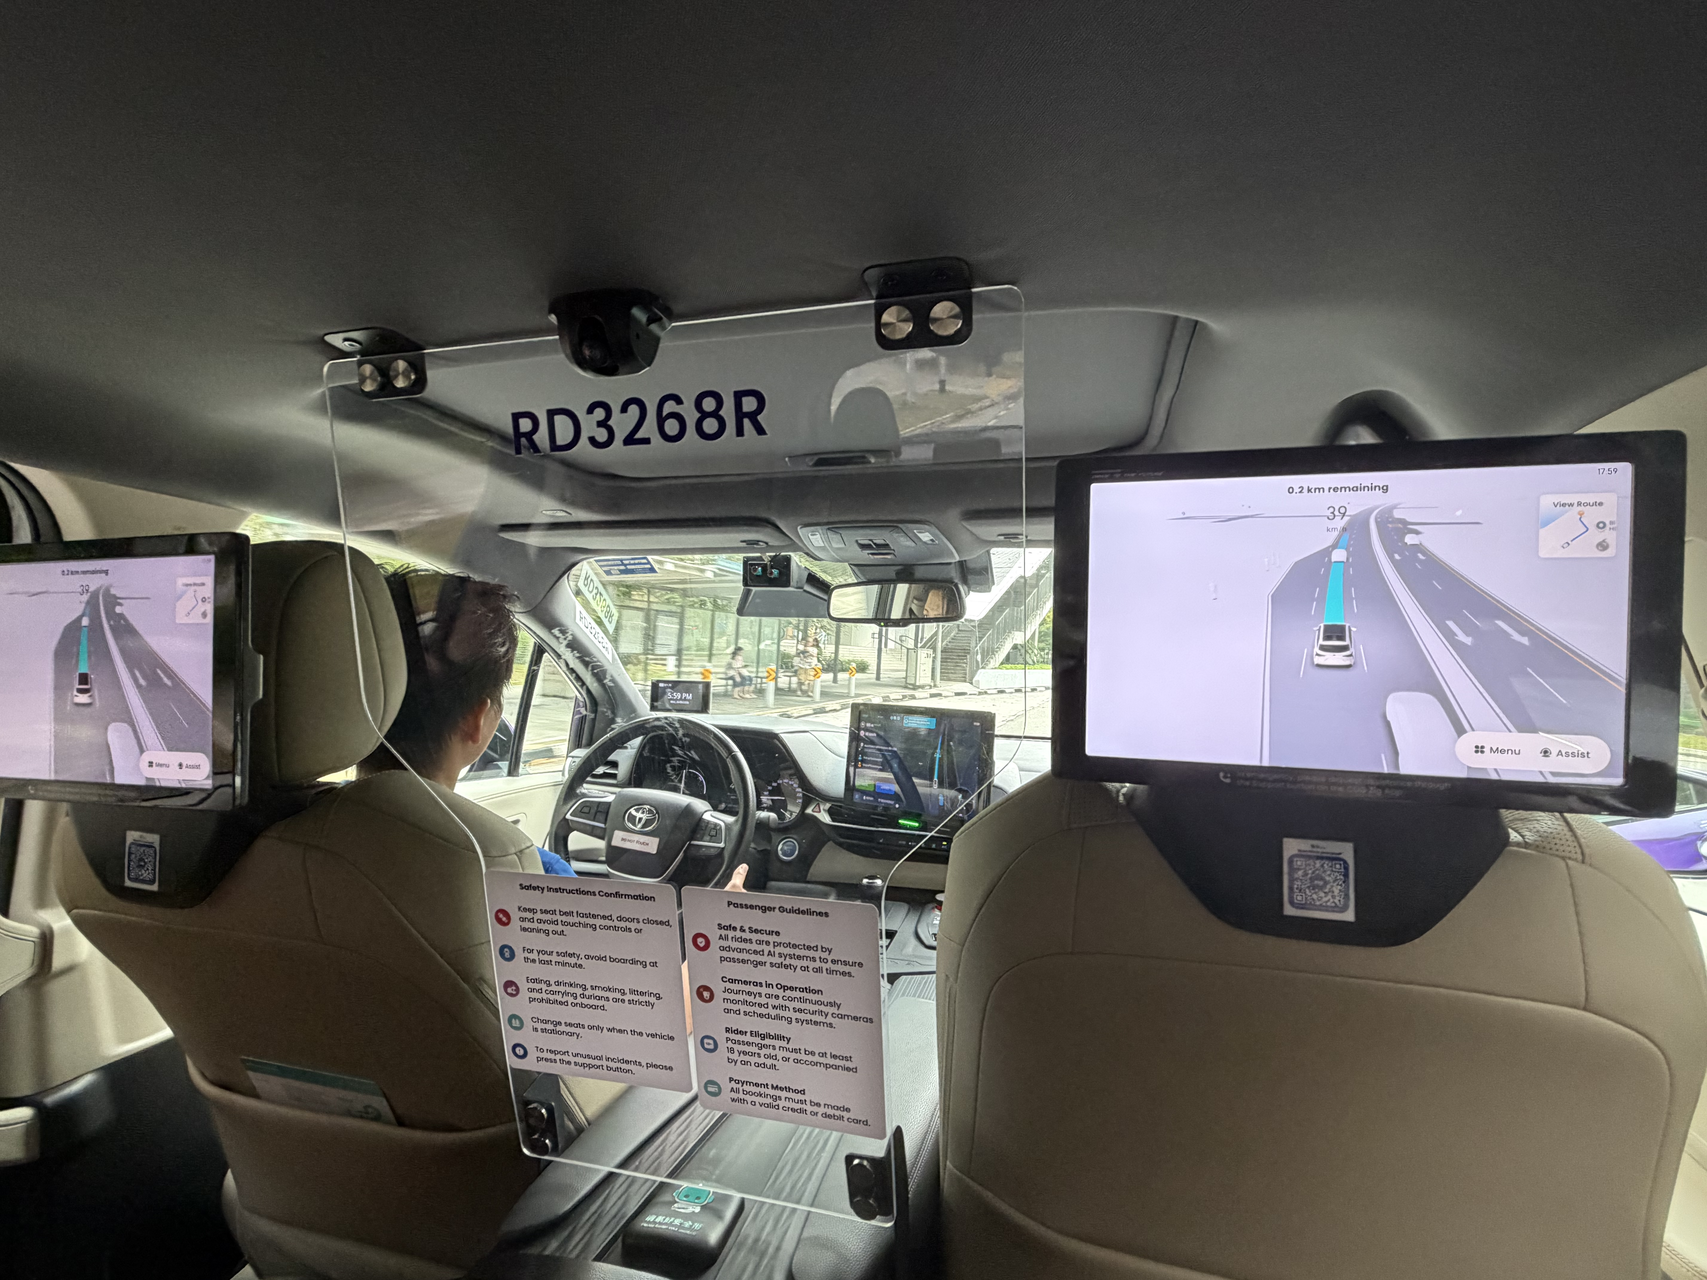
If driverless cars already work, why aren’t they everywhere?
Sumsub Launches Workforce Verification as Deepfake Risks Grow
ByteDance’s AI-enhanced short-drama app eclipses China’s Netflix rivals combined

Timo Joins Top 10 Banks in Vietnam by Customer Satisfaction
Payment Agility and Modernisation for the Age of Intelligence