
When Your Shopping App Offers a Loan, Who Profits Behind the Scenes?
Embedded finance has seen substantial growth across Asia Pacific in the last 12 to 18 months, driven by new partnerships and independent activities in fintech and digital banking, according to David Becker of Mambu. This expansion is particularly notable in markets like the Philippines, Indonesia, and Thailand, where large underbanked populations fuel demand for lending and e-wallets.
The core question in embedded finance is who captures value when platforms own the user journey and data, but financial institutions provide licenses, balance sheets, and risk management. This dynamic has led some platforms to acquire banking capabilities and some fintechs to pursue licenses, blurring traditional roles. The market is evolving towards a model where players focus on their strengths.
Partnerships are essential for navigating this evolving landscape. TNG Digital, for instance, positions itself as an open platform, leveraging its 27 million users in Malaysia to deliver financial services. By collaborating with banks and financial institutions for compliance and regulatory heavy lifting, TNG Digital avoids trying to be a bank itself, playing to its strength in reach and user engagement.
A key challenge behind the seamless user experience of embedded finance is the complex task of underwriting risk. Boost Bank’s Deputy CEO, YM Ungku Norliza Syazwan, highlights that a robust underwriting engine and a healthy loan book are critical for profitable revenue sharing. This requires partners to agree on a single underwriting model, a process that demands time, data analysis, and learning from past losses.
The future of embedded finance appears to be moving towards open finance, with Malaysia targeting a major milestone by Q1 2027. Raymond Ng of Revolut Singapore and Southeast Asia anticipates that open finance, combined with AI, will enable faster data access, more efficient KYC and credit scoring, and the rapid development of new products, potentially transforming the entire fintech and digital banking landscape.
Share this article
Related reading
6 stories
Beijing moves to steady A-share market after sharp tech sell-off
Job order disorder
Scage Future Provides Business Update on Deliveries, Technology Portfolio and Growth Initiatives; Initiates Regular Investor Communication

Anthropic just took steps to protect Claude's feelings. Here's what that means.
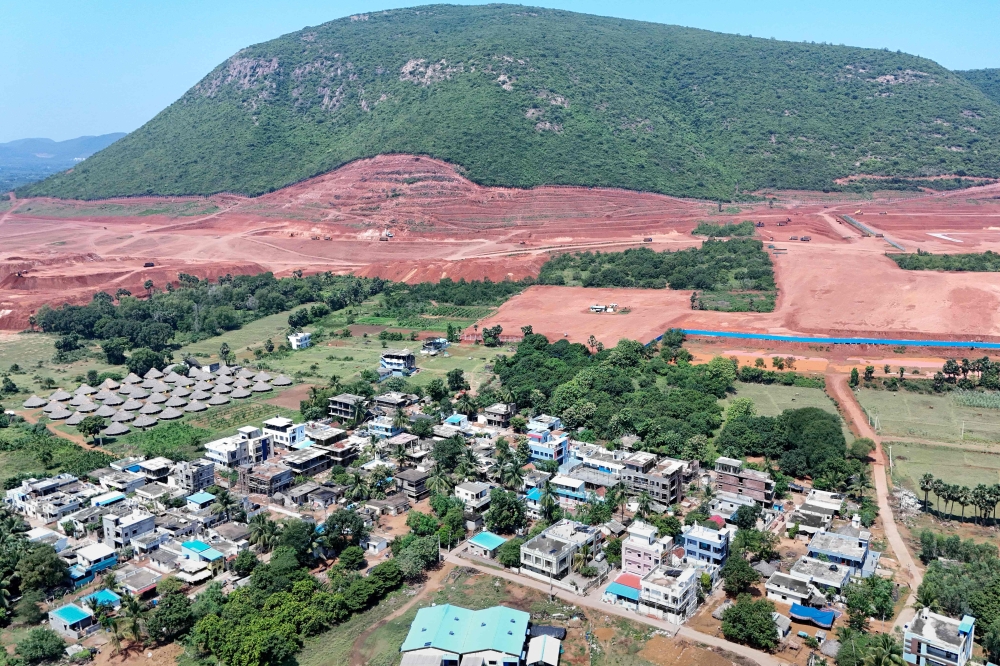
Power, water, jobs: Google’s India AI mega‑centre ignites debate over costs, benefits and community impact
